
Good Morning!
Good Morning!
I’ve heard from several of you this past week. It sounds like the guys from Minnesota are harvesting a dandy of a crop. I’ve heard mixed reviews around Iowa and Nebraska, while northern Illinois sounds similar to the rest of the state in that there’s some good, bad and otherwise. For us, we’re finishing our fieldwork this weekend, so we’re about out of stuff to do in the field. It’s dry as a bone here-even ripping, we aren’t finding any moisture to speak of. We’re forecasted to get some rain over the next several days, so I’m hopeful we’ll get it. Some would like to start fall anhydrous, but I’m not sure there’s enough moisture in the ground. Keep me posted on your progress and how things are turning out if you get a chance. I appreciate the feedback. mbennett@agmarket.net.
For the podcast this week, I had another of my co-workers, Tim Strunk join me to talk wheat acres and how that could impact corn and soybean acres this coming year. 2027 Acreage Outlook: 4M More Wheat Acres & What it Means for Corn & Beans
Both corn and beans lost more ground on the week. While beans started the week on the defensive due to Brazil’s Lula getting elected, they stabilized as the week progressed. Harvest activity likely kept pressure onl. Outside markets likely provided a mixed bias:
- The US Dollar was up .101 at 101.749.
- December crude oil was up .85 at 104.12.
- The DOW was down 476 points at 51,918.
CORN
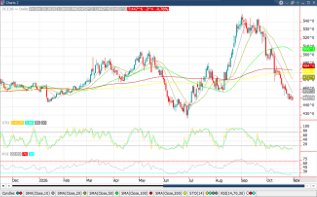
December ‘26 corn continued lower on the week as harvest activity and fund selling provided pressure. On Friday, Dec settled at $4.47 ¾, down 3 ½. This was 4 ½ off the high and ¼ off the low. Dec lost 8 ¼ cents for the week. The COT report showed funds sold another 90k contracts by Tuesday’s close, reducing their long to 56k. Technically, the corn market is quite oversold and below all moving averages. We’re 20 cents from the low for the year, so we’ve literally knocked this corn market back to levels we haven’t seen since the summer. Demand has picked up a bit, but with the extra bushels USDA has dumped in the market’s lap, funds appear to have no interest in owning corn. It seems likely we’ll have funds at a flat position if not short when we see next week’s COT report. I still believe the yield is off of what the USDA says, but when we find that out will be tough to outguess. While long-term I think corn is good property, we may have to show some patience.
DEMAND
Corn demand was strong this past week. Exports came in at 1.304 mmt, so it was down a shade but a big number. Ethanol production increased to 1,118 mbpd, while stocks were down, even with the increase. Basis was still improving in some areas:
• My local basis: 20 under Dec (no change)
• Decatur: 5 over the Dec (no change)
• St. Louis River: 25 over the Dec (narrowed 9 cents)
CASH CORN
Cash prices in most places were a little lower, following the board prices. In some other areas, cash was flat as basis improved. Anywhere harvest is close to wrapping up, basis is likely to narrow as originators look to lock up final bushels. If you’re in an area with a wide basis, this drop really stings I know. For bushels that have to go across the scale, I’m still of the opinion that having some corn ownership is where I want to be. Corn in the bin will likely see a basis appreciation as we typically see. While we don’t know if this sell-off continues, my opinion is we have seen the worst of it. I don’t mind even some DP as I’ve stated lately. While commercial storage of any type isn’t something I love, I know many have to deliver to the elevator and don’t need al their money during fall. Long story short, this has been a gut-punch for anyone long corn. Locking in those worst-case scenarios is something I’m sure people get tired of hearing me say, but this market of late is exactly why I try to handle marketing in this manner.
2027 CORN
December 2027 corn ended the week at $4.87 ½, down 7 ½ for the week. Dec27 is clearly following the rest of the corn complex lower. I find it interesting we’re seeing so much weakness with new-crop. If we end up losing a few acres of ’27, it could be an issue satisfying demand. While the USDA’s last two reports have taken the wind out of our sails in a big way, strong demand both in the US and globally are very much still intact. With some reporting first-crop corn acres in Brazil are likely off from a year ago and concerns about safrinha crop due to this Super El Nino, my opinion is Dec27 corn should be one of the most supported contracts we have. I’m in no hurry to sell more, especially with the bushels already sold vs fertilizer purchases. If a person wants to set some floors to lock in profitability, that sounds good-so long as there’s some flex in the plan. Here is the link for more info on the AgMarket app. https://hubs.li/Q03qt2Qd0
Corn Market Theme: The corn market remains under pressure. I look for a more supported market as harvest winds down.
BEANS
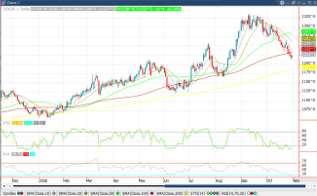
Beans had a rough start to the week before stabilizing but lost plenty of ground. On Friday, November beans settled at $12.22 ¼, up 2 ½. This was 6 off the high and 5 off the low. Beans lost 34 ¼ cents on the week. December meal lost 21.5 on the week at 324.6, while soy oil was down .93, settling at 65.90. The COT report showed funds sold 21k contracts, decreasing their long to 185k by Tuesday’s close. From a technical standpoint, the bean market broke right through the 100-day moving average at the start of the week before stabilizing. With Lula winning the election in Brazil, the Real moved lower and most in the market feel this will make US beans tough to sell on the world market. While exports have been strong for beans due to the US/China agreement put in place, domestic demand has also been strong. So, on the demand front, both US and world, we’re running full-steam ahead. Keeping a lid on prices is likely talk of a bigger US bean yield as yield reports have been impressive start to finish. This bean market has been resilient, all things considered, but it appears a move down to longer-term support at the 200-day moving average is looking like a better possibility if we don’t see buying come in this week. That would be down to $11.87 ½ or another 35 cents lower. The last thing on this bean market-weather issues in Brazil/Argentina will be closely monitored with Super El Nino. This market looks rough right now but could take off big-time if South American production dips.
DEMAND
Soybean export sales were off from last week but still impressive at 2.576 mmt. Basis was steady to improved:
• My local beans: 25 under the Nov (no change)
• Decatur: 6 over the Jan (8 cents improved)
• River: 24 over the Jan (2 cents improved)
CASH BEANS
Cash beans were again lower but with basis continuing to see some improvement, we didn’t lose everything we lost on the board. Bean basis in areas with crush plants has been strong, while river basis has also performed well with big shipments of late. While having ownership of corn is something I’ve been a fan of, I think beans are worth keeping ownership is as well-at least until we see what production looks like in South America.
2027 BEANS
Nov 2027 beans settled at $12.09, down 22 cents on the week. New-crop beans are like new-crop corn in that neither will want to lose many acres. The video link I posted above talks about the fact we’ll have less corn and soybean acres combined most likely-due to a big wheat acre increase. With excellent insurance guarantees for both HRW and SRW wheat, I’m assuming wheat acres will be up at least 3 million. We have to acknowledge many of these acres could be double-crop potential, so bean acres could hold together fairly well. I just feel with the big push for more crush in the US, beans won’t easily give up acres for 2027. Given I’ve sold a few beans already for next year, I’m in no hurry to sell more. With that said, hedging beans over $12 isn’t a bad deal for most growers, so it would be understandable to lock a decent percentage in provided there’s some flex in the plan.
Bean Market Theme: The bean market was hurt by geo-political issues this past week. Hopefully, we’ll see prices hold this coming week and funds don’t liquidate their long like they have in corn.
As always, use the AgMarket.Net Profitability App to help you figure your break-evens and put your plan in place:
Let me know if I can help in any way. These markets are tricky, but with a plan in place, we can take the emotion out and make better decisions.