Good Morning!
Good Morning!
I’ve had a little more sleep this week than last as we had the crop put away as of Saturday night. We’ve been wanting to do some fieldwork, but were expecting rain this past week, so we were hoping to get a good shower first. We had up to a half-inch, so it was better than nothing-but we’re still awfully dry. Heading into the weekend, temps plummeted from the 80s and 90s we’ve seen of late with this front that came through-frost advisories are in place, so quite the contrast. Interestingly, this coming week we’re supposed to be right back in the 80s. A big question for many around here is whether we put on fall anhydrous and when that happens. Given longer-term forecasts are for a warm and wet winter, it’s got me thinking hard about what to do. I appreciate all of the yield reports. Keep them coming and stay safe! mbennett@agmarket.net.
For the podcast this week, I had on Maree Johnson, who is an AgMarket broker out of Iowa to talk crop size, quality and thoughts about USDA moving forward. Is USDA's 181.2 Corn Real? Grain Merchandiser Exposes Iowa & Nebraska Yields
The corn market lost some ground on the week while beans took the brunt of trader selling. With a low crush number this week and brisk activity, even big export news couldn’t keep beans from moving lower. Outside markets likely provided a positive bias:
- The US Dollar was down .364 at 101.658.
- November crude oil was up 9.56 at 101.41.
- The DOW was up 288 points at 52,214.
CORN
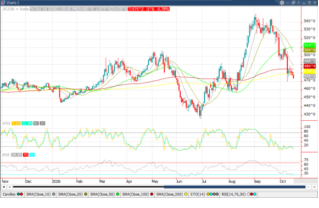
December ‘26 corn again lost ground on the week, likely due to harvest pressure and spill-over weakness from soybeans. On Friday, Dec settled at $4.74 ¼, down 3 ¾. This was 6 ¾ off the high and 1 ¼ off the low. Dec lost 5 ½ cents for the week but were higher on the week during Friday’s session before moving lower. The COT report showed funds sold 86k contracts by Tuesday’s close, reducing their long to 231k. Technically, the corn market saw closes at or above the 200-day moving average up until Thursday but closed below it the last two sessions of the week. While harvest pressure would typically be a culprit during a big harvest week, I’m not sure farmers are selling across the scale after this big run-up, according to originators we keep up with. There’s some of course, but much of the selling is likely continued fund selling as the trade continues to digest the bigger crop. While our team has done our best to figure out if this yield is in fact legitimate, it would seem unlikely USDA would lower it much after raising from September to October-at least it would be quite rare. I still feel corn in the bin likely has good value, particularly as we see basis already improving when we’re not even halfway complete. The bushels going across the scale that aren’t contracted is what many are likely struggling with. For me, DP on some of those bushels should be considered if those costs aren’t out of hand. Demand for corn is solid, but there’s no doubt it will take some time to get this market to turn-and it very well may not get back to where we were before if South America doesn’t have weather issues.
DEMAND
Corn demand was strong this past week. Exports came in at 1.122 mmt, so it was up over 300k from a week ago. Ethanol production increased to 1,065 mbpd, while stocks were up a bit. Basis was improving in most areas:
• My local basis: 20 under Dec (12 cents improved)
• Decatur: 5 over the Dec (narrowed 5 cents)
• St. Louis River: option the Dec (narrowed 13 cents)
CASH CORN
Cash prices were steady or even a bit better in most areas even with the lower futures prices. Given basis improvements, effective cash prices were better than a week ago, and in some cases, quite a bit better. There are areas close to wrapping up harvest, and as we generally see, basis for those folks narrows a ton as elevators try to lock up remaining bushels. However, even in Iowa this past week where harvest was in full-swing we saw cash prices at $5 for a couple of facilities! 20 over the board is a great fall bid and indicates to me origination isn’t quite as easy as some had assumed. For those with HTAs, I’d watch these basis levels for an opportunity to lock in a good basis. Some end-users are another 15-20 cents better starting Nov or Dec 1, so keep that in mind. For those trying to decide what to do with bushels going across the scale, you might again look at some DP instead of cash, especially if your basis hasn’t improved at all. Lastly, I’m still a fan of owning corn at home or having ownership with bushels that have been sold. I wouldn’t get carried away, but after the big sell-off, demand has remained strong and I would expect this market to bounce back at some point in here. It may take a bit but with lower prices, demand is unlikely to do anything but increase.
2027 CORN
December 2027 corn ended the week at $5.06 ¾, down 5 for the week. Dec27 is staying above $5 for now, but we keep leaking off a bit. I’m not bearish Dec27 corn at all right now, even with the additional bushels USDA dumped in our lap. Given what is expected to be much higher wheat acres due to a strong wheat insurance price and huge bean demand, acres are likely to be at a premium. I see no issue with having some corn locked in, but for me, I don’t want to get too aggressive unless I have some flex in the plan. A strong floor to allow us to give this some time might be a consideration, so let us know if you’d like a customized plan. As always, it all comes down to locking in profitability. Here is the link for more info on the AgMarket app. https://hubs.li/Q03qt2Qd0
Corn Market Theme: The corn market has seen futures leak lower while cash prices are steady to higher. Basis and spreads tell me this crop has been overstated.
BEANS
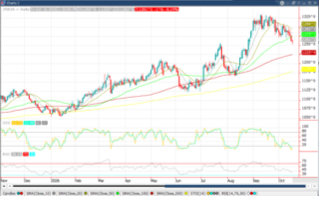
Beans had a rough week as selling continued in the bean complex. On Friday, November beans settled at $12.61 ¼, down 1 ¾. This was 4 off the high and 8 off the low. Beans lost 30 ¾ cents on the week. December meal lost 8.5 on the week at 357.1, while soy oil was down .89, settling at 67.13. The COT report showed funds sold 14k contracts, decreasing their long to 237k by Tuesday’s close. From a technical standpoint, the bean market ended the week poorly, closing below the 50-day moving average the final two sessions. It’s possible we could see a test of the 100-day, which would be another 35 cents lower, down at $12.25. With September crush this past week coming in at 196.3 mb, we were well off the average trade estimate of 203.7. We were also lower than last year’s Sep number, which is the first time we’ve seen a month below the previous year in well over a year. It’s hard to be bearish based on the fact that in September there were many facilities that simply couldn’t get ahold of the beans. In all honesty, export announcements were excellent this last week, but it wasn’t enough to slow down the selling. Contrary to corn, we’re hearing quite a few beans are being sold across the scale, which is adding to the selling pressure. While I felt good about beans before this past week, the technical action is concerning. IF South America continues to have non-threatening weather, it may be tough to see this bean market rally back towards the levels we were at.
DEMAND
Soybean export sales were up around 25k at 574k. Basis was steady to improved:
• My local beans: 25 under the Nov (narrowed 10 cents)
• Decatur: 10 over the Nov (25 cents improved)
• River: 8 over the Nov (a nickel improved)
CASH BEANS
Cash beans were lower, despite basis improving in many areas. While bean harvest is farther along than corn, we saw similar basis improvements. With harvest likely improving rapidly this week, farmer selling likely added to the pressure on cash bean prices as some of those lofty basis levels we saw when many in the west were muddy have now subsided. As with corn, those bushels on HTAs might get basis improvements worth looing at, so keep tabs on them. If a person has excellent bean yields, as we’re hearing from many growers, there’s no harm in selling the beans and being happy with a solid net income. I know many want to re-own beans, and I am in the same camp-but I’d do so in a non-marginable way. Buying a few options just in case South America’s weather turns hot and dry for Brazil and quite wet for Argentina as El Nino typically provides-isn’t a bad idea at all.
2027 BEANS
Nov 2027 beans settled at $12.40 ¾, down 22 ½ cents on the week. New-crop beans lost some ground this past week and closed right at the 50-dma. While I see the balance sheet as quite snug with current numbers, IF we see USDA raise yields again (and I expect that to happen) it will loosen up stocks a bit. Regardless, with such a big crop this year and increasing demand keeping stocks/use somewhat tight, I think the acreage fight could still be on. I fully expect wheat acres to be up at least two-million acres, maybe more. Given that, we likely have less combined corn and bean acres-and with big demand, neither will want to give up acres easily.
Bean Market Theme: The bean market gave up some ground this week and looks susceptible. Prices compared to years past are still attractive, so risk-management or simply selling some beans is tough to argue with.
As always, use the AgMarket.Net Profitability App to help you figure your break-evens and put your plan in place:
Let me know if I can help in any way. These markets are tricky, but with a plan in place, we can take the emotion out and make better decisions.