
Good Morning!
Good Morning!
I hope you’re making good progress on your operation. For ours, we’ve had some good luck this fall when it comes to weather. For most of the week we were forecasted 1-2 inches of rain out of the big system moving through. On Thursday night into Friday morning, we had no more than a half-inch of rain. In all honesty, a little more rain wouldn’t have upset any of us around here as hard as everyone’s been going. We didn’t get much where we were picking corn, so we got after it around noon and were set to finish that farm on Saturday. It looks like good harvest weather for the next couple of weeks, so without breakdowns, we’ll be wrapping up in the next week to ten days. It looks like most of the corn-belt will be rolling here in early-October with weather maps indicating great harvest weather. I know for many of you it’s been an aggravation the last few weeks watching it rain. I’ve been there and it’s not fun. Keep me posted on harvest. mbennett@agmarket.net.
For the podcast this week, I was in the combine again talking about the September Quarterly Stocks Report. USDA Quarterly Grain Stocks Breakdown: Corn Surprise, Soybean Tariffs & Basis Outlook
The corn and bean markets lost some ground on the week. With a bearish surprise for the corn market on stocks and a market disappointed with US/Chinese news when it comes to soybeans, sellers were active. While weather wasn’t necessarily bearish with how wet much of the country was, the forecast market seemed to be more of what the trade was focused on-and it’s improved. Outside markets likely provided a positive bias:
- The US Dollar was up 1.009 at 101.717.
- November crude oil was down 1.30 at 91.11.
- The DOW was down 686 points at 51,477.
CORN
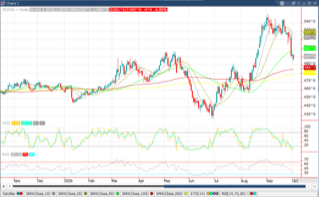
December ‘26 corn took it on the chin, mostly due to a bearish stocks report. On Friday, Dec settled at $4.97 ¾, down 4 ½. This was 4 ½ off the high and 2 ¾ off the low. Dec lost 30 ½ for the week-the first close below $5 since August 19th. The COT report showed funds sold 37k contracts, reducing their long to 378k. While they had been selling some already, this was as of Tuesday’s close-and on Wednesday, there’s no doubt the funds were in selling corn. I expect a big adjustment on this position when we look at it in a week. The stocks situation is interesting in that they essentially ‘found’ some corn even with the big demand we saw unfold. They adjusted last year’s crop 57 million-bushels lower due to smaller harvested acres, but still showed 170mb more corn on hand than the trade guessed. Given USDA has the October report out this Friday, they’ll pull those stocks into the old-crop and new-crop balance sheet, just like they pulled them out back in the July report after June quarterly stocks were bullish. Where does this leave us? We have huge demand still with a much smaller crop this year than last due to lower acres and yield. Given we’re in harvest, it takes quite a bit to rally a market, but we tend to see corn gain some value once harvest gets halfway done-we need a couple of weeks to get there. I like corn ownership especially after the big drop we’ve seen. We’ll learn more on Friday with the WASDE report out on how this might play out heading into the last quarter of the year.
DEMAND
Corn demand was off a bit this past week. Exports came in at 536k, so it was down 300k from a week ago. Ethanol dropped again to 1,007 mbpd, while stocks were down again. Basis was mixed:
• My local basis: 32 under Dec (no change)
• Decatur: 15 under Dec (no change)
• St. Louis River: 25 under Dec (narrowed 4 cents)
CASH CORN
Cash prices got beat up this past week. While the report was the main culprit, it sure seems like most years we see some of the lowest prices during harvest. There’s no way of knowing if this year will be the same, but my hunch is we’ll see prices improve due to strong demand and a much smaller 2026 crop than a year ago. Nothing has changed in my mind about putting all the corn in the bin you possibly can as basis is likely to improve as it typically does post-harvest and futures may need to stay supported for a variety of reasons. Given world stocks/use ratios have plummeted over the last several years and US stocks/use is forecasted for this current marketing year 300+ mb lower than the marketing year we just exited, there is plenty of room for optimism. The big question on cash corn is what to do with bushels going across the scale. I’ve historically not been a huge fan of commercial storage, but putting some bushels in storage and spreading out your risk might not be a bad idea with expectations basis improvements will help pay for that storage and any price rally could make it a solid move. Selling some that’s going across the scale and re-owning that corn with options is also a good move as we get cash in hand and lock in a worst-case scenario. Regardless, let us know if you need help on your plan as I know it can be a tough decision. One thing is for sure, it’s nice to see some of the better harvest bids in recent memory.
2027 CORN
December 2027 corn ended the week at $5.16 ½, down 11 ½ for the week. Dec27 didn’t lose near as much ground as nearby contracts. This is due to what I talked about before-a need for more corn this coming year. While corn to fertilizer still looks better than a year ago, that gap has narrowed a bit. Either way, getting some corn on the books when booking inputs still makes sense to me. While we can have reasons to be bullish, it’s tough to argue with a person locking in profit on a portion of their production. We didn’t have that luxury the last three years. Here is the link for more info on the AgMarket app. https://hubs.li/Q03qt2Qd0
Corn Market Theme: The corn market took a hit this past week as harvest looks to be in full-swing coming up. October USDA on Friday will be closely watched.
BEANS
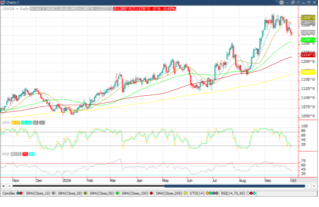
Beans lost some ground on the week, mostly due to the US/Chinese trade situation. On Friday, November beans settled at $12.78 ¼, down 5 ¾. This was 7 ½ off the high and 5 off the low. Beans lost 40 ¾ cents on the week. October meal plummeted 29.2 on the week at 344.7, while soy oil was up .95, settling at 68.21. The COT report showed funds sold 24k contracts, reducing their long to 241k by Tuesday’s close. From a technical standpoint, the bean market moved back below the 10 and 20-day moving averages and looks susceptible to more selling. However, production both in the US and SA is of concern as quality and yield issues where we’ve seen harvest delays could be problematic-while some areas in Brazil need rain to make some progress planting. The bean market has plenty going for it as well, but the problem again is some in the trade were hopeful we’d sell even more beans than the 25mmt China committed to. With the tariff staying in place on US beans, that doesn’t seem likely. Still, we’re looking at a tight stocks situation here in the US moving forward. World stocks are unlikely to grow without record crops in both hemispheres so the pressure is on to see big crops. I’m not bearish beans after this pull-back, but that’s just my opinion.
DEMAND
Soybean export sales were up big, almost doubling a week ago levels at 1m tons. Basis was widening:
• My local beans: 40 under the Nov (no change)
• Decatur: 15 under the Nov (widened 5 cents)
• River: 3 over the Nov (narrowed 19 cents)
CASH BEANS
Cash beans were much lower on the week in most places. The river bid cut the board losses in half for producers hauling in there, highlighting a still strong basis in Iowa as well as more export activity. With cash beans, if a person can store some at home and keep the moisture intact, I like some bean ownership on the farm. For bushels going across the scale, I again would consider some commercial storage. Bean basis locally for me is 40 under, and I expect that to change big-time as we get past harvest, so some of that storage cost likely gets paid by basis narrowing. Either way, having some ownership on these beans makes sense to me, but I wouldn’t do it in a marginable position. I like locking in worst-case scenarios we can live with and that’s much easier to do with prices we’re looking at this year.
2027 BEANS
Nov 2027 beans settled at $12.53 ¼, down 23 ½ on the week. New-crop beans performed similarly to Dec27 corn in that they didn’t lose near the ground as nearby contracts. This as well is due to the ‘need’ for big bean acres in 2027. IF this crop is adjusted lower on Friday due to weather issues and harvest delays, the balance sheet on beans will be quite tight-highlighting the need for acres. When we look at the weather we’ve seen, most feel rain in the west will bring quite a few wheat acres back into the mix-so we’re setting up for an acreage battle due to big-time demand for both corn and beans. As I’ve said recently, this market could have some wild swings over the next year, so having a few beans locked in at the best levels we could hedge at in several years isn’t a bad idea. However, I’m not going to be too aggressive just yet given this strong demand, tough harvest situation in 2026 and a strong El Nino that hasn’t backed off just yet.
Bean Market Theme: The bean market lost ground on the week. Much of the short-term direction for this bean market will depend on the upcoming October WASDE report on Friday.
As always, use the AgMarket.Net Profitability App to help you figure your break-evens and put your plan in place:
Let me know if I can help in any way. These markets are tricky, but with a plan in place, we can take the emotion out and make better decisions.