
Good Morning!
Good Morning!
It’s hard to believe but September is here and harvest will be full-swing before we know it. We don’t have anyone close to home who’s harvesting, but it’s not far away. We chopped silage this past week, so we’re another couple of weeks most likely. Given temps are in the 90s this coming week, things are going to change fast. I was at Becknology Days on Thursday and Friday, and man there was a huge crowd. They couldn’t have asked for better weather for it, and the people showed up, biggest crowd they’d ever had attend. I couldn’t stay for Saturday, as our nephew is getting married-Abileen, the youngest is the flower girl as well. With all the kids at home, it’s going to be a great weekend. Back to the great weather I mentioned of late, I’d think we had great grain-fill weather the second half of August, so hopefully we built some test weight and got those pods filled on the beans. I know with all of you I visited with there’s everything from excellent crops to serious challenges. I appreciate the input and hope harvest goes better than expected for those of you who are about to begin. mbennett@agmarket.net.
The podcast this past week detailed how the ProFarmer crop tour could impact this market along with how the tour generally compares to USDA numbers. Pro Farmer Tour Shocks Corn Yields: How High Can Prices Go?
The corn and bean markets both rallied sharply again this past week. With the tour results a known, tensions in the Black Sea region driving wheat prices higher likely supported corn and beans. Interestingly, outside markets likely provided a negative bias:
- The US Dollar was up .929 at 99.658.
- October crude oil was down 3.66 at 83.4.
- The DOW was up 231 points at 53,584.
CORN
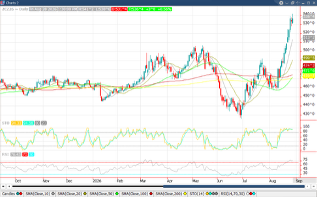
September ‘26 corn rallied 4 out of 5 days for the second week in a row. On Friday, Sep settled at $5.12, up 1 ¾. This was 5 ½ off the high and 4 ¾ off the low. Sep rallied 28 ½ cents for the week and 53 cents in the last two weeks. Technically, this corn market broke out on the monthly continuous chart, indicating this market could have quite a bit more upside. All contracts on corn made news highs this past week for their respective months as fund buying ramped up. The commitment-of-traders report showed funds bought a whopping 136k contracts, taking their net long to 317k. While this isn’t a record just yet, it could slow the buying somewhat given just how many longs we have in the market. Crop size is a tough thing to quantify this year. There’s no doubt some of the fringe areas have struggled with excessive heat, particularly out west. I-state growers likely lost enough nitrogen to take the shine off more record yields, while we turned around and finished in good fashion, likely holding onto some bushels. My best guess is 178.5 at this point, but in all honesty, we won’t have a great handle on it until harvest starts and more importantly is finished. While it’s easy to be bullish at this point, I’m still in the camp of incremental sales into rallies while keeping a long bias on as many bushels as possible on a limited-risk basis.
DEMAND
Corn demand was mixed this past week. Exports came in at 31 kmt for old-crop and 1.066m for new, down for old and up for new. Ethanol posted an increase on the week, increasing by about 23k barrels/day to 1,112. Stocks were up. Basis was mixed:
• My local basis: 5 under Sep (a nickel improved)
• Decatur: 15 over Sep (a dime wider)
• St. Louis River: 14 over Sep (4 cents improved)
CASH CORN
Cash prices were strong again this week. While basis widened in some areas, it’s understandable as harvest gets underway. Keep in mind the bid for corn after the 16th of September at ADM Decatur is 25 cents wider, which is something we’ll all likely see once we see bushels coming in earnest. Next week, cash corn will be our 2026 crop as far as I’m writing. As growers, it’s that time of year. Those who have some old corn sitting around, it might be a great idea to get into some of your corn and blend it off, taking advantage of quick-ship bids and/or drying deals. While I expect corn to be supported until we sort this crop size out, it would be tough to assume we don’t see some harvest pressure. Manage risk accordingly.
2026 CORN
December 2026 corn ended the week at $5.36 ½, up 28 for the week and 53 ½ over the last two weeks. Dec posted yet another new contract high this week. Given many growers in the heart of the corn-belt could get $5 out of the field at $5.25-5.30, it was impressive to see Dec move above and beyond that, let alone settle up there. While everyone is bulled up and for good reason, for those who feel confident in APH and above yields, it’s tough to argue with selling some corn at these levels. Heck, these are the highest prices we’ve seen in years. While I still feel like corn in the bin will be great property, those bushels heading to the elevator will need priced this fall unless a person is storing commercially. For those wanting to sell and keep ownership of the bushels, it makes sense to buy a call or call spread. I’m not a fan of a marginable position in these instances as I don’t want to make a good sale a bad one due to something unforeseen. I think the best way to handle this market is to lock in net income while keeping some flex. Here is the link for more info on the AgMarket app. https://hubs.li/Q03qt2Qd0
Corn Market Theme: The corn market looks strong but could see a setback heading into harvest. Incrementally rewarding this rally makes good business sense.
BEANS
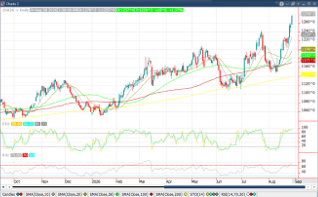
Beans also rallied four of five days on the week. September beans settled at $12.76 ¼, up 19 ¾. This was 2 off the high and 18 ¾ off the low. Beans rallied 51 ¼ cents on the week and 98 ½ over the last two weeks. Sep meal settled up 20.5 on the week at 338.2, while soy oil was up 1.24, settling at 70.59. The COT report showed funds bought another 49k contracts, bringing their long to just over 200k. From a technical standpoint, this bean market also looks like it could take off and go. All contracts are above all moving averages and made new highs for the week. At the same time, we’re finishing this crop in many areas of the corn-belt in good fashion with August rain quite timely. Cooler temps of late will be replaced by heat in many areas in the coming days which should bring harvest along. With President Trump considering granting more small refinery exemptions for the 2025 RFS, the ag sector has been aggravated to say the least. At the same time, he announced they’re discussing the possibility of restoring some of those gallons with mandates for the next couple of years, restoring what has been a growing crush industry. These petitions for waiver will be closely watched by the bean market. With beans fairly tight going into harvest, we’ll likely see basis go from quite narrow to a fair amount wider. As we consider bean price direction, we must consider what this strong El Nino could do to world production. I believe the market is trading it to a fair degree. On the one hand, it’s offering opportunity, while I know many are so bulled up they don’t want to sell anything. I’d consider spreading the risk out with some sales at profitable levels.
DEMAND
Soybean export sales were huge overall. 74k mt were posted for old-crop, while new-crop sales were impressive at 2.478 mt. Basis was mixed/widening:
• My local beans: option the Nov (unchanged)
• Decatur: 30 over Nov (a dime wider)
• River: 20 over Nov (unchanged)
CASH BEANS
Cash beans were up big on the week. These old beans are essentially just beans here soon. As with corn, the basis really changes from the here and now to harvest timeframe. Cash bids are 38 cents better than fall bids in our area, which start around Sep 21. While I like having some bean ownership, I know many will want to sell at harvest. Keeping some ownership should be a consideration the more aggressive we get, preferably with calls or a call spread.
2026 BEANS
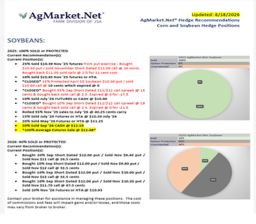
Nov 2026 beans settled at $12.88, up 48 ½ on the week and 95 ½ over the last two weeks. New-crop beans getting the rain we saw for many in August typically don’t rally like they have. However, lower pod counts on the PF tour were closely watched, even though the final yield for PF came in at 53.3, above USDA’s 52.7. Given it appears production could increase, the board continued to see buying. It’s likely a fair bit of the funds’ interest is based on potential weather issues in South America. I believe at current prices, many can make decent money, especially if they’re expecting a bean crop that’s better-than-average. Locking in a worst-case scenario where we make money is tough to argue with after the years we’ve just experienced. I will likely have many of my beans priced this fall while keeping some flexibility with calls or call spreads for potential upside as I rarely store beans. Let us know if we can help you with your marketing plan.
Bean Market Theme: The bean market continues the strong rally. Taking advantage of a rally like this requires an incremental sale here and there.
As always, use the AgMarket.Net Profitability App to help you figure your break-evens and put your plan in place:
Let me know if I can help in any way. These markets are tricky, but with a plan in place, we can take the emotion out and make better decisions.