
Good Morning!
Good Morning!
It’s been a hot one this week. With temps hovering around 100 degrees each day, it feels more like July than September. One thing it’s done is bring the crops along quickly, particularly corn. One of the guys in my office hand-shelled corn at 24% late last week and delivered out of that field on Wednesday at 19%! It’s been drying a point+ per day, so we’ll likely get started on corn this coming week. Beans have been turning big-time as well, and I can only assume they’ll come a little quicker with this heat. My forecast shows mid-80s to mid-90s for the next two weeks, so once we get started, we’re going to have to get after it. Some of the kids’ activities have been canceled due to excessive heat, and my only comment there is I don’t remember having anything canceled due to heat. I celebrated another year on Friday, and while birthdays aren’t as exciting as they used to be, I gotta feel blessed with the family, farm and people I get to work with. Keep me posted on harvest if possible. mbennett@agmarket.net.
The podcast this past week was a broad look at the rally and what it might mean for fall prices as well as acres this coming year. Grain Prices Hit Fresh Highs: How to Lock In Fertilizer Ratios & Profits
The corn market didn’t do much on the week, while beans were up some. With harvest getting started, there was likely some hedge pressure, while longs continued to enter the market. Outside markets likely provided a positive bias:
- The US Dollar was down .508 at 99.150.
- October crude oil was up 8.08 at 91.08.
- The DOW was down 144 points at 53,440.
CORN
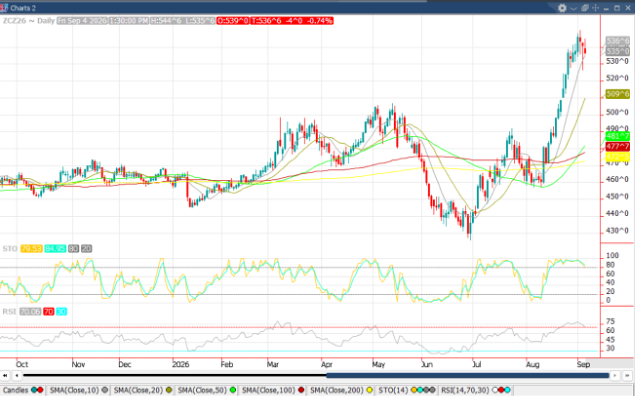
December ‘26 corn saw new highs for the week but didn’t end up going anywhere by the end of the week. On Friday, Sep settled at $5.36 ¾, down 4. This was 4 ¾ off the high and 5 ¾ off the low. Dec rallied ¼ penny for the week. Technically, this corn market settled back on the 10-day moving average after posting a new high at $5.49 ¾ on Wednesday. The commitment of traders showed funds buying another 84k contracts, ballooning their long to just over 400k. With the USDA report this coming week, there’s no doubt we could see some volatility. Given the highest prices we’ve seen in the last three years, it’s tough to ignore making some sales, especially for those who feel like they need to get caught up. For the report, my AgMarket group pegged the crop at 178.8, a drop from USDA but not near as low as ProFarmer. We see the stocks/usage dipping below 10%, but I believe the market is well aware we’ve gotten that low already. I’m not bearish by any means, but I struggle once again to think these price levels are a bad place to lock in some net income.
DEMAND
Corn demand was mixed this past week. Exports came in at -826 kmt for old-crop and 1.966m for new-with this week, we finished the old-crop marketing year and started the new. Ethanol was steady on the week, while stocks were down. Basis was mixed:
• My local basis: 30 under Dec (similar bid as vs Sep)
• Decatur: 8 under Dec (again similar bid)
• St. Louis River: 26 under Dec (widened 15 cents)
CASH CORN
Cash prices were steady this past week in most areas. At the river, we saw some widening as harvest was getting started. With a strong export program right up to harvest, some of those river facilities were likely running thin. Cash corn for our purposes this week is one and the same with fall corn now that harvest is here and we’re in the new marketing year. I realize many will be running in the next week or so. It’s fortunate to see highs of not only the year but the last three years as harvest approaches. While I’ve said I like corn ownership, laying off some risk at prices like we’re seeing should be considered given profitability. The bushels that have to go to town would be the easiest ones to sell or have sold given commercial storage costs. Those bin bushels might be considered for hedges or floors as well. May corn at $5.60 and July a couple pennies better would be tough to pass up I’d think. I know most of us are bulled up-but keep your wits and be willing to take profits on at least a portion of your crop when it’s there. It’s a luxury we have this year.
2027 CORN
December 2027 corn ended the week at $5.36 ¼, up 9 ¼ for the week. Dec27 posted a new contract high this week. If there’s one contract I’ve felt like the risk/reward of being long or giving it time to hedge risk, it’s been new-crop. Given how tight our stocks are currently pegged, there’s no doubt we need an acreage increase for 2027. I don’t believe beans can give up acres, while July wheat surged to $8+ this past week. The potential for an acreage battle is certainly present. With all this being said, current fertilizer prices at this price for corn look better than a year ago. Therefore, those booking their fertilizer needs might consider hedging enough corn to cover some of those costs. It’s a great way to lock in a better ratio of corn/fert than we saw a year ago. Here is the link for more info on the AgMarket app. https://hubs.li/Q03qt2Qd0
Corn Market Theme: The corn market has paused as we await the September USDA report. Best advice I can give is to base our marketing on profit margins. While I personally like some flexibility, the main goal must be locking in profitable worst-case scenarios.
BEANS
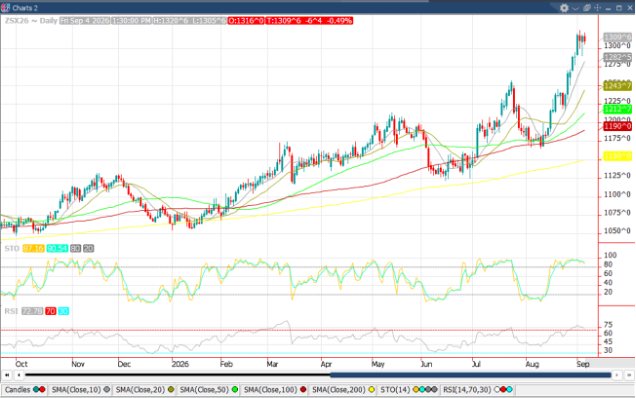
Beans fared better than corn this week, gaining some ground. November beans settled at $13.09, down 6 ½ on Friday. This was 11 off the high and 4 off the low. Beans rallied 21 ¾ cents on the week and $1.17 over the last three weeks. October meal settled up 5.7 on the week at 348.2, while soy oil was down 1.93, settling at 68.69. The COT report showed funds bought another 34k contracts, bringing their long to 235k. From a technical standpoint, this bean market remains above all moving averages but looks as though it’s also taking a pause after making a new contract high. With news this week that the small-refinery waivers were being granted for many while re-allocating the gallons to 2026-27, the market took this information as a positive apparently. With all things considered, strong demand for beans in the US and globally necessitate big production globally. Given the Super El Nino, I assume the trade is concerned any hiccup in production could cause buyers to scramble this coming year. As producers, locking in profits at levels like we’re currently seeing must be considered on an incremental basis. If you can lock in a profitable year, it’s tough to argue with.
DEMAND
Soybean export sales were down but still impressive. -94k mt were posted for old-crop, while new-crop sales were impressive at 1.948 mt. Basis was mixed/widening:
• My local beans: option the Nov (unchanged)
• Decatur: 30 over Nov (unchanged)
• River: option the Nov (20 cents wider)
CASH BEANS
Cash beans were up in most areas. While the river also widened for beans, it’s due to harvest getting started. Crushers on the other hand are rolling right along with margins remaining strong. As with corn, cash beans are just beans at this point, with most premiums for early beans starting to erode as we get into harvest. While beans could still rally substantia IF we see weather issues in South America, locking in some of these price levels makes great sense. Keeping some flexibility is something I like as well, with call spreads my preferred method. Either way, the main thing I’d want to consider is what kind of profit is on the table as we get into these beans. While it’s impossible to outguess this bean market, it’s a great situation when looking at our prices currently.
2026 BEANS
Nov 2027 beans settled at $12.56, up 14 ½ on the week. New-crop beans as I mentioned previously will likely do what they can to hang onto as many acres as possible. This new-crop export program for beans has been nothing short of impressive with China buying like it’s going out of style of late. Of the 25mmt, we estimate China is well over 40% of the way there already when it comes to purchases. IF they indeed buy 25, given the crush situation, beans will likely be very tight even with a much bigger crop than a year ago. Therefore, for new-crop, I’d expect some acreage battle. With that being said, I see no issue hedging off some beans at prices this high. We haven’t had many years where we could hedge beans at prices like this for the next year’s crop. Heck, I haven’t sold any beans the last three years in advance of the crop anywhere near these levels. While I’d keep some flex if getting aggressive on percentages, a worst case scenario above $12.50 looks profitable to me.
Bean Market Theme: The bean market is still in rally mode but has slowed a bit. Expect some volatility around the report and beginning of harvest. Incremental sales at profitable levels is tough to argue with.
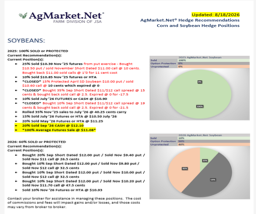
As always, use the AgMarket.Net Profitability App to help you figure your break-evens and put your plan in place:
Let me know if I can help in any way. These markets are tricky, but with a plan in place, we can take the emotion out and make better decisions.