
Good Morning!
Good Morning!
It’s hard to believe September is coming to an end already. With harvest in plenty of different stages for many of us, it’s a busy time for all. We continue to have a good run, with beans likely to be wrapped up in the next day or so. We still have plenty of corn to shell, and the weather this week might determine how quickly we get back going. I believe all of our corn is under 17 or 18%, even the May-planted. It’s incredible how quickly we saw corn dry down this year. In talking to a buddy up by Waterloo, Iowa, his corn is still 27-28%. It’s incredible the differences we’ve seen this year. Our corn and beans are good but certainly nothing close to what we’ve raised before. Much of that is again due to the big weather disparities. As many of you experience during harvest, the only time I’ve seen my family the last several days is when they come to the field. It’s a grind for sure, so be safe if you’re running hard. For more on AgMarket, click here. https://hubs.li/Q03qt2Qd0
The markets started the week sharply lower on Monday as details emerged on the President Trump meeting with Xi. With tariff reduction on corn and other ag products but not soybeans, we saw beans take a hit. Fortunately, beans had a nice little rebound on Tuesday. Outside markets likely had a negative impact:
- The US Dollar settled up .190 at 101.116.
- November crude oil settled down 3.22 at 89.38.
- The DOW settled down 135 points at 51,702.
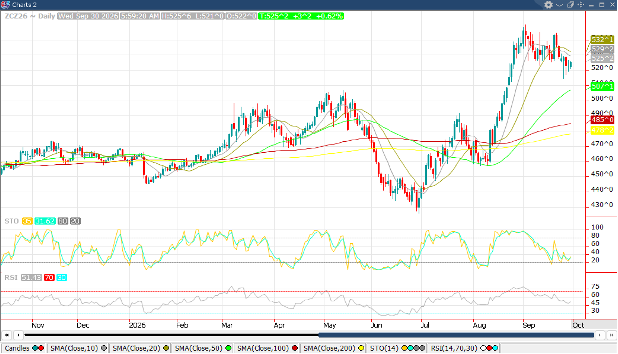
Corn – After settling down a nickel on Monday, the corn market was slightly lower on Tuesday. December corn closed down 1 at $5.22. This was 4 ½ off the high and 2 ¾ off the low. Corn export inspections were above expectations at 1.6 mmt. These shipments were 300k lower than a week ago. Corn harvest came in at 18% complete, which matches the 5-year-average. With Iowa having another wet week, there remains concern about harvest progress and quality of the corn still in the field. Talk of disease issues, corn sprouting etc have made the rounds with no good idea of how widespread it might be. The September Quarterly Stocks report is out today at 11 am, and if this report is anything like the ones we’ve seen in the past, some surprises could be in store. There’s no doubt demand was incredible last year-the big question is where did stocks end up? Did they overstate the 2025 corn crop a bit? We’ll find out more later today. Dec27 corn settled down 2 ¾ at $5.22 ¼.
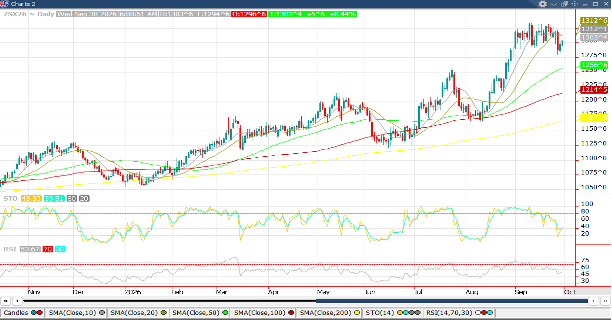
Soybeans – Soybeans got smoked on Monday before getting back some of those losses on Tuesday. November beans settled up 9 ½ at $12.97 ¾. This was 6 ¼ off the high and 13 ¾ off the low. October soybean meal was down 1.6 at 360.1, while soy oil was down .15 at 67.11. Weekly inspections showed bean shipments at 1.2 mmt, an increase from a week ago levels and above expectations. The bean crop is 17% harvested, which is in-line of the 5-year-average. As we’ve discussed on weather, there are beans in more states than just Iowa that are ready to be cut, but it’s hard to cut beans in the rain. It’s been on the trades’ mind, but what impacted us the most was certainly US/Chinese relations. While they’ve bought half or more of the 25mmt they promised to buy, not reducing the 10% tariff on US beans disappointed the trade. State-owned companies have been buying these beans, while privately-owned companies say US is not competitive due to the tariff. Any hopes of going above and beyond the 25 mmt mark seems unlikely, and that’s why we lost so much ground on Monday. Overall, I’m not bearish beans though-not until we get a better handle on harvest and crop size. We need huge crops out of the US and SA as well due to record demand. Nov27 beans settled at $12.64, up 7.
Matt Bennett
815-665-0462 – Work
@chief321 - Twitter
mbennett@agmarket.net – E-mail