
Good Morning!
Good Morning!
Harvest is complete for most but not all who are reading this. After hearing from several of you this past week, I have to think those with big yields aren’t reaching out. I know some of my clients in N Iowa into Minnesota shared their yields with me-and they’re impressive indeed. However, much of the feedback from the newsletter is lower yields than a year ago. With USDA’s November report out next week, we’ll continue to learn more about the crop. It sure has been rough of late watching these markets. Keeping perspective with the blessings we all have is a must when mired in markets that don’t seem to know any direction but lower. Keep me posted if you haven’t had a chance to yet. I appreciate the feedback. mbennett@agmarket.net.
For the podcast this week, I detailed the November USDA Supply and Demand report, which is to be released on Tuesday and talked about slow cash movement. November WASDE Preview: Corn & Soybean Yield Estimates, Carryout & Fund Positioning
Both corn and beans continued the death spiral we’ve seen the last few weeks with corn losing a few cents while beans were a little weaker, relatively speaking. While the election didn’t likely have much to do with price action, there was certainly plenty of action in many different markets on the week. Outside markets provided a decidedly negative bias:
- The US Dollar was up .430 at 102.179.
- December crude oil plunged 13.29 to 90.83.
- The DOW was down 533 points at 51,385.
CORN
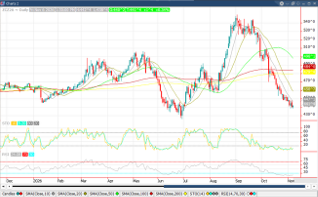
December ‘26 corn continued lower once again but at least closed the week on a positive note. On Friday, Dec settled at $4.41 ½, up 1 ½. This was 1 off the high and 3 off the low. Dec lost 6 ¼ cents for the week. The COT report showed funds sold another 79k contracts by Tuesday’s close, which now puts the funds at a 23k contract short position. It’s incredible how quickly the funds went from a record long to short-just a few weeks. Technically, the corn market has been oversold for the last few weeks but tried to find some footing. While Dec isn’t to the low for the year just yet, given we are at the lowest level since pre-pollination, a bounce would be tough to argue with. The November USDA report is Tuesday with the average trade guess predicting corn yields move lower. The market sure doesn’t act like it thinks corn yields will move lower. While I don’t expect USDA to do much on this report, I believe we’ll ultimately find US production has been overstated-whether we find that out in January or next summer is hard to predict, but I think it eventually plays out. For those bin bushels, a person is going to need to remain patient for now. I’m not bearish corn after this drop-while I don’t expect us to get everything back we lost, I’d be surprised if we don’t see a modest rally paired with post-harvest basis gains.
DEMAND
Corn demand was strong again this past week. Exports came in at 1.295 mmt, down just 10kt and a solid number. Ethanol production increased to 1,143 mbpd, while stocks were down again-impressive considering bigger production. Basis was still improving in some areas:
• My local basis: 20 under Dec (no change)
• Decatur: 10 over the Dec (narrowed 5 cents)
• St. Louis River: 25 over the Dec (no change)
CASH CORN
Cash prices were steady to a bit lower as basis was improving in some areas while corn prices on the board were a bit lower. With harvest getting finished or close to it in many areas, basis is improving to try and latch onto those later bushels. As far as this old-corn goes, I’m not interested in selling down here. There’s no way of knowing if this debacle we all went through is something we’ll have to deal with for long, but I still think corn will be good property moving forward. As always, what matters most is locking in net income, so anytime you can look at making more sales and keeping your net income on the farm in the black, it’s tough to argue with.
2027 CORN
December 2027 corn ended the week at $4.85 ¼, down 2 ¼ for the week. Dec27 appears to be finding some support as well. I’d find it hard to believe we’ll see Dec27 go down much more considering inputs haven’t backed off. What kind of acreage can we expect with wheat acres likely up while beans presumably won’t give up their acreage easily? It’s a tough call, but I would expect Dec27 to hang in there and try to maintain some acres. I’m not a fan of extending sales anytime soon, but if a person can call it a profit, there’s nothing wrong with locking in some more bushels. Keeping profitable with your worst-case scenarios is a great spot to be in. As always, I’d want some flex in the plan, but locking in net income is tough to argue with. Here is the link for more info on the AgMarket app. https://hubs.li/Q03qt2Qd0
Corn Market Theme: The corn market should find support with the funds now short this market. Without a bearish surprise on the USDA report, look for corn to stabilize.
BEANS
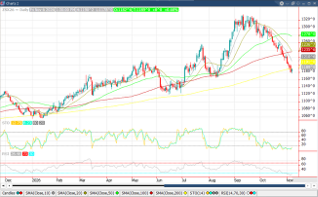
Beans continued lower this past week as sellers didn’t back off much. On Friday, November beans settled at $11.89, up 8. This was 1 ¼ off the high and 11 off the low. Beans lost 33 ¼ cents on the week. December meal lost 5.4 on the week at 319.2, while soy oil was down 3.64, settling at 62.26. The COT report showed funds sold 53k contracts, decreasing their long to 133k by Tuesday’s close. From a technical standpoint, the bean market broke through the 200-day moving average at the end of the week and tried to settle back up on it at around $11.89 ¼. This bean market had been resilient for some time but has buckled with talks of a yield increase in the US along with political headwinds from Brazil’s election. I’d be surprised if traders go short this bean market without seeing how production looks for Brazil this growing season. With models trending warmer and drier, it’s tough for me to think anyone would want to get caught on the wrong side of what could be a volatile market. While there are no guarantees, I’d expect beans to try and find some support here barring a super-bearish report on Tuesday.
DEMAND
Soybean export sales were off quite a bit from last week but a respectable number at 1.456 mmt. Basis was steady to improved:
• My local beans: 30 under the Jan (no change)
• Decatur: 8 over the Jan (2 cents improved)
• River: 33 over the Jan (9 cents improved)
CASH BEANS
Cash beans were again lower. While basis improved in some areas, it wasn’t enough to off-set the drop on the board. Bean export demand has been excellent while domestic demand continues to grow. As with corn, having some bean ownership moving forward seems like a good idea, especially with the unknowns surrounding Brazil’s production. I’m not necessarily bullish beans, but a flexible approach to marketing these beans makes sense to me. If we have them all sold, buying a call or two might be worth considering.
2027 BEANS
Nov 2027 beans settled at $11.77 ½, down 31 ½ on the week. New-crop beans certainly had a tougher week than new-crop corn did. Part of this may be due to thoughts this ’26 crop is bigger than we previously thought. If we can roll into 2027 with a few more beans, the ‘need’ for acres this coming year may not seem to be so great. I’m not convinced of that just yet. While I like locking in bean profitability when it’s on the table, I know many of you didn’t want to book many beans a year ahead of harvest. Every year is certainly different, and it’s certainly not for the faint of heart trying to lock in profit margins when they’re not all that common the last few years. If we can help with a plan, be sure and let us know.
Bean Market Theme: The bean market continued lower in anticipation of this November WASDE. Hopefully, we’ll see some support come in as the trade gets a handle on weather risk out of South America.
As always, use the AgMarket.Net Profitability App to help you figure your break-evens and put your plan in place:
Let me know if I can help in any way. These markets are tricky, but with a plan in place, we can take the emotion out and make better decisions.